Percentage of Americans That Own Stock: Why Most Don’t Get Rich From It
Sept 10, 2026
The percentage of Americans who own stocks has risen dramatically over the past several decades, but a crucial distinction is often lost in the headline numbers: owning stocks is not the same as owning enough stocks to build substantial wealth.
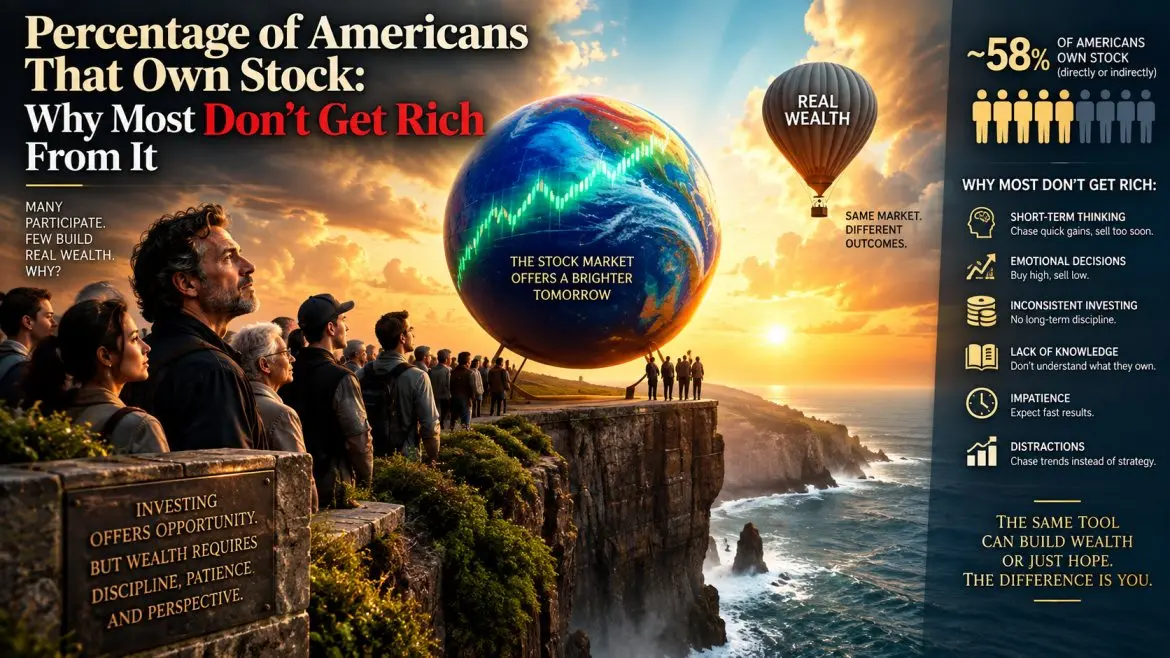
The latest data make that distinction impossible to ignore. The Federal Reserve’s 2022 Survey of Consumer Finances found that 58% of U.S. families owned stocks either directly or indirectly through retirement accounts, mutual funds, and similar vehicles, up from 53% in 2019. Gallup’s latest available survey found that 62% of American adults reported owning stock in 2025, matching 2024 and remaining well above the sub-60% readings that dominated much of the period after the 2008 financial crisis.
That sounds like democratization of wealth. It is, to an extent, but the deeper numbers tell a different story. In 2022, the median stock holding among families that owned stocks was only $12,600 for the bottom half of income groups, compared with $608,000 for the top income decile. The difference is roughly 48 times, meaning that a 7% annual return on the top group’s median holding would generate about $42,560, more than three times the entire median stock balance of the bottom half.
The real question is therefore not simply how many Americans own stocks. It is how much capital they own, how long they own it, and whether that capital is large enough to materially change their financial trajectory.
American Stock Ownership Has Exploded Since the 1950s
Stock ownership was once a privilege concentrated among a relatively small portion of American households. Historical New York Stock Exchange data show that only about 6% of U.S. adults owned equities in 1952. That figure rose to 17% by 1975, 27% by 1985, 36% by 1995, and 39% by 1999.
The transformation accelerated as mutual funds, employer-sponsored retirement accounts, IRAs, and later online brokerage platforms made equity ownership increasingly accessible. The modern investor does not necessarily buy individual shares, because stock ownership can occur indirectly through retirement accounts and pooled investment vehicles. The historical progression is worth seeing in one place:
| Year | Approx. U.S. Stock Ownership | Measurement |
|---|---|---|
| 1952 | 6% | U.S. adults |
| 1965 | 16% | U.S. adults |
| 1975 | 17% | U.S. adults |
| 1985 | 27% | U.S. adults |
| 1995 | 36% | U.S. adults |
| 1999 | 39% | U.S. adults |
| 2001 | 51.9% | Households, direct + indirect |
| 2010 | ~47% | Households, direct + indirect |
| 2019 | 53% | Families, direct + indirect |
| 2022 | 58% | Families, direct + indirect |
| 2025 | 62% | U.S. adults, Gallup |
The table should not be interpreted as a perfectly continuous statistical series because the historical sources use different populations and definitions. Nevertheless, the direction is unmistakable: equity ownership has moved from a relatively narrow form of participation toward a mainstream component of American household finance.
The 2022 Fed Data Reveal the Real Problem
The Federal Reserve’s 2022 SCF provides a much more revealing picture than the headline participation number. Stock ownership increased across income groups between 2019 and 2022. Yet participation remained sharply unequal: only 34% of families in the bottom half of the income distribution owned stocks, compared with 78% of upper-middle-income families and 95% of families in the top income decile.
The difference becomes even more striking when we examine the size of the portfolios.
| Income Group | Stock Ownership, 2022 | Median Stock Holdings Among Owners |
|---|---|---|
| Bottom 50% | 34% | $12,600 |
| Upper-middle | 78% | $53,200 |
| Top 10% | 95% | $608,000 |
The ownership percentage therefore hides an enormous difference in economic impact. Two households can both be classified as “stockholders,” yet one may own $10,000 of equities while another owns $600,000 or several million dollars.
More Ownership Has Not Eliminated the Wealth Gap
The Federal Reserve’s Distributional Financial Accounts provide an even clearer picture of where equity wealth sits today. As of the first quarter of 2026, the top 1% of households held approximately 50.2% of all corporate equities and mutual fund shares, while the bottom 50% held only about 1.1%.
That is the number that should dominate any serious discussion of stock ownership and wealth inequality. The stock market can therefore become more accessible without becoming equally distributed. Millions of Americans can participate in the market while the overwhelming majority of the financial benefit from rising equity values continues to accrue to households that already possess substantial capital.
The Federal Reserve’s latest wealth data show the same pattern across the broader balance sheet. In the first quarter of 2026, the bottom 50% held roughly $0.59 trillion in corporate equities and mutual fund shares, compared with $13.33 trillion for the top 0.1% and $14.31 trillion for the next 0.9% of the top 1%. The market therefore does not merely reward participation. It rewards the amount of capital participating.
Why More Americans Own Stocks but Still Don’t Get Rich
There are several reasons why stock ownership does not automatically translate into wealth creation. The first is starting capital. A 10% return on $10,000 produces $1,000, while the same return on $1 million produces $100,000. The percentage return is identical, but the economic consequence is radically different.
The second is consistency. Wealth compounds when capital remains invested and additional capital continues to be deployed. A household that owns stocks sporadically, sells during market crashes, or repeatedly moves in and out of the market can capture far less of the market’s long-term compounding than the headline return suggests.
The third is psychological behaviour. Investors tend to become most enthusiastic after markets have already risen substantially and most fearful after markets have fallen sharply. This creates a devastating pattern in which investors can buy high because they feel confident and sell low because they become frightened.
This is where mass psychology becomes central. The market does not merely transfer returns according to time and capital. It can also transfer wealth from emotionally reactive investors to those capable of remaining disciplined when the crowd becomes extreme.
The Wealthy Have Another Advantage: They Can Buy the Panic
The distribution of stock ownership creates another important psychological and financial asymmetry. A wealthy investor can maintain liquidity, survive volatility, and deploy additional capital when markets collapse. A lower-wealth investor may have to sell investments during a crisis because of unemployment, debt, unexpected expenses, or the need for immediate cash.
This creates a vicious cycle. Those with substantial capital can sometimes treat a market crash as a buying opportunity, while those with limited financial reserves may experience the same crash as a threat to their financial survival.
That does not mean every wealthy investor is a good investor or every lower-income investor is a poor one. It means that capital creates optionality, and optionality becomes extraordinarily valuable during market extremes. The investor who has cash available when everyone else needs liquidity possesses a structural advantage.
Stock Ownership Is Increasing, but So Is the Importance of Behaviour
The expansion of retirement accounts and low-cost investment vehicles has made stock ownership easier than ever. Yet access alone does not create wealth. An investor can own an index fund for thirty years and benefit enormously from compounding. Another investor can own the same fund but repeatedly abandon it during crashes and re-enter after markets recover. Both technically participated in the market, but their outcomes can be dramatically different.
This is why financial literacy should not be reduced to teaching people how to open brokerage accounts. Investors need to understand valuation, risk, compounding, market cycles, cognitive bias, and the psychological forces that cause investors to abandon otherwise sound strategies at precisely the wrong time. The greatest threat is often not the market. It is the investor’s reaction to the market.
Long-Term Investing Still Matters
The historical evidence supports the basic principle that equities can be an effective long-term wealth-building asset, but the word long-term is doing considerable work. Benjamin Graham emphasized the distinction between investing and speculation, while the broader value-investing tradition stresses buying assets at reasonable prices and maintaining a margin of safety. That principle remains relevant because a good asset purchased at an extreme valuation can produce disappointing returns, while a quality asset purchased during a period of excessive pessimism can provide extraordinary upside.
Dollar-cost averaging can also help investors maintain discipline by systematically deploying capital rather than attempting to predict every short-term market movement. Its greatest advantage is psychological: it reduces the temptation to make every investment decision based on the emotional environment of the moment.
For more experienced investors, however, market extremes can provide additional opportunities. When fear becomes extreme, investors who have already identified quality companies can use valuation-based entry points, cash-secured puts, or other structured strategies to deploy capital while the crowd is focused on escape.
The Real Democratization of Wealth
The increase in American stock ownership is undeniably significant. Going from roughly 6% of adults owning equities in 1952 to more than 60% of adults reporting stock ownership today represents an extraordinary transformation in access to financial markets.
But access is not the same as equality. The modern American economy has succeeded in putting stock-market participation within reach of a much larger portion of the population, while simultaneously maintaining a massive disparity in the amount of equity capital owned by different groups. The top 1% now control roughly half of corporate equities and mutual fund shares, while the bottom half controls around 1%.
That is the paradox. More Americans own stocks than ever before, yet the people who own the most stocks continue to capture the overwhelming share of the wealth generated by those assets.
The solution is therefore not simply to increase participation. It is to increase meaningful participation, improve financial literacy, encourage long-term ownership, and most importantly, help investors understand the psychological mistakes that cause them to sabotage compounding.
Conclusion: Owning Stocks Is the Beginning, Not the Wealth Strategy
The percentage of Americans who own stock has risen enormously since the middle of the twentieth century. From a market largely reserved for a relatively small investor class, equities have become embedded in retirement accounts, mutual funds, brokerage accounts, and household financial planning.
But the headline statistic can be misleading. Owning $10,000 of stocks and owning $1 million of stocks places two households in the same statistical category while producing radically different financial outcomes. The real wealth-building equation is therefore capital × time × compounding × discipline. Remove any one of those elements and the result can be dramatically weaker.
The next step is psychological. Investors must learn to remain invested when markets become frightening, avoid becoming euphoric when markets become fashionable, and recognize that the greatest opportunities often emerge when the crowd is least comfortable acting.
Stock ownership has become democratic. Meaningful wealth creation has not. The difference is not merely who owns stocks. It is who owns enough of them, who remains invested long enough, who continuously adds capital, and who has the psychological discipline to exploit the market’s inevitable extremes rather than becoming a victim of them.
Unconventional Articles